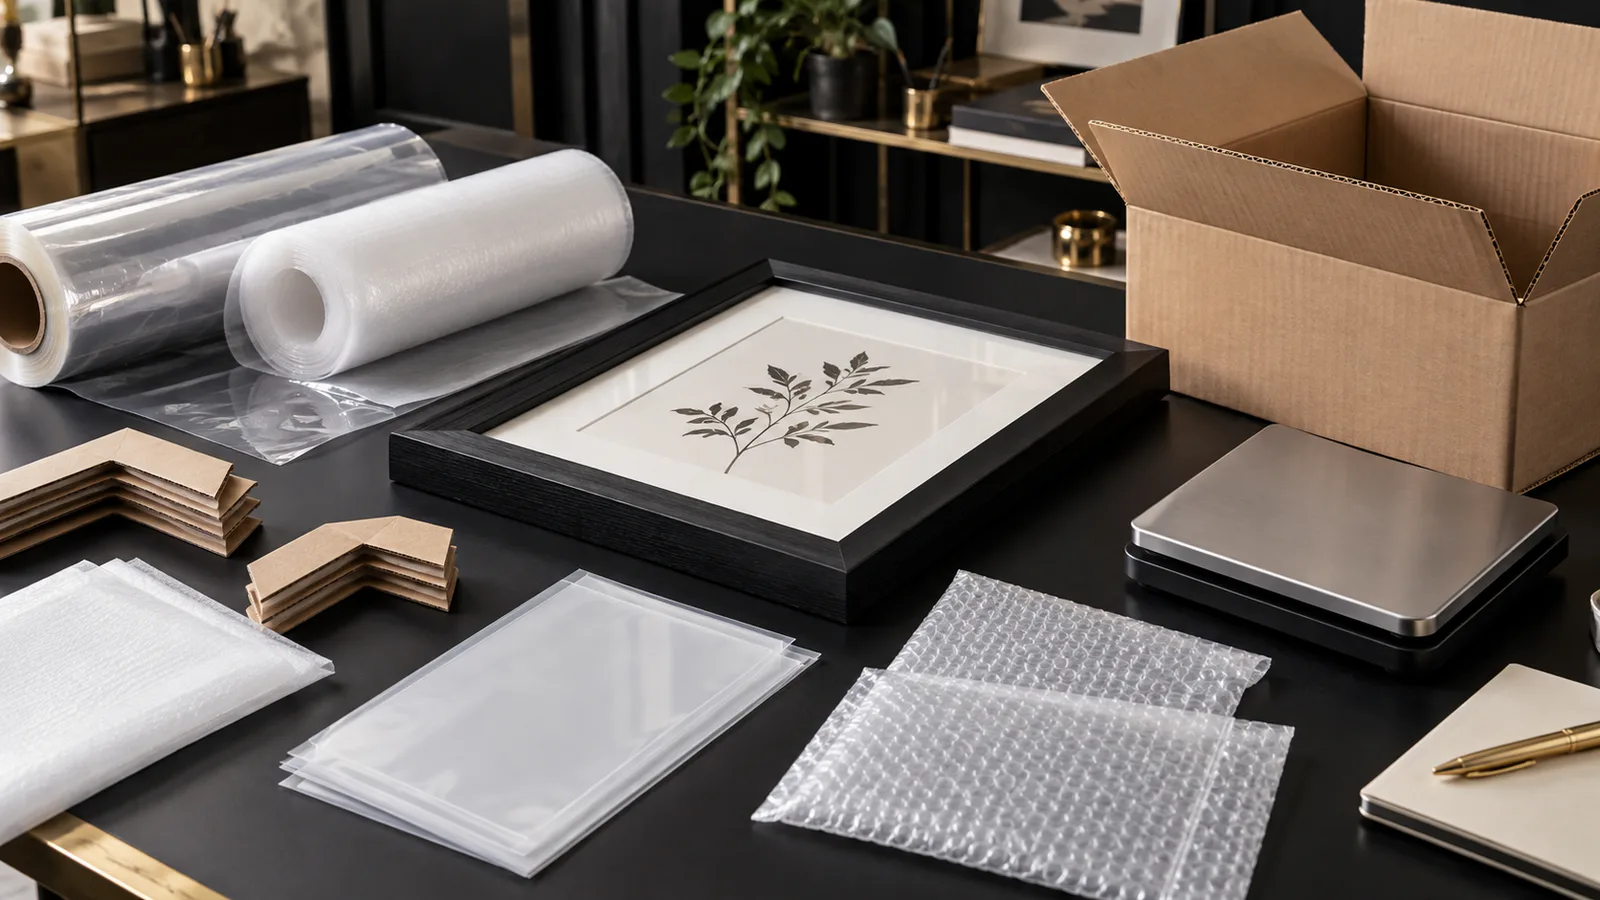
A display frame can be mostly wood, metal, glass or acrylic and still arrive in the United Kingdom with several finished plastic packaging components. Protective film, a polyethylene sleeve, bubble cushioning, foam corners, tape and an accessory bag may each need a separate Plastic Packaging Tax review. Treating the whole pack as one percentage can hide the very information the importer needs.
This guide is for UK importers, private-label frame brands, packaging engineers, finance teams and overseas OEM suppliers building an evidence pack for Plastic Packaging Tax, or PPT. It is separate from the UK's packaging extended-producer-responsibility rules. It does not classify a component, calculate a tax return, confirm recycled content or replace current HMRC guidance and advice from a qualified UK tax professional.
Keep PPT separate from packaging EPR
Plastic Packaging Tax and packaging EPR may both use packaging data, but they ask different questions. PPT focuses on finished plastic packaging components manufactured in or imported into the UK, including whether they contain at least 30% recycled plastic and whether registration thresholds are met. Packaging EPR has its own producer, reporting and fee framework. A company can need one, both or neither depending on its facts.
Create separate compliance workstreams with a shared source BOM. Name the owner, reporting period, units and decision record for each. Do not label a component “EPR exempt” and carry that conclusion into the tax file. Likewise, paying PPT does not complete EPR obligations. The supplier can issue one accurate physical data pack, while the importer and its advisers apply each regime's rules independently.
Identify the finished component, not just the material
HMRC explains that PPT applies when an individual plastic packaging component is finished in the UK or when finished plastic packaging is imported. Packaging can be one component, such as a bag, or several components working together. For a frame, a protective sleeve, bubble pouch, plastic corner, tape, label film and accessory bag should not be merged simply because they arrive in the same carton.
Assign a stable component code. Record function, material, supplier, manufacturing process, finished state, dimensions, gross component weight, plastic weight, recycled-plastic weight, pack position and revision. Photograph the component by itself and in the packed frame. This lets the importer connect a tax conclusion to a real item instead of a broad phrase such as “standard export packaging.”
Ask whether the component performs a packaging function
Official guidance says packaging components may contain, protect, handle, present or deliver goods. A clear film that protects glazing, a bag around the frame and a foam block that prevents corner damage can all perform packaging functions even though the frame itself is not plastic. Function should be assessed for the specific component and use.
Do not assume a part is outside scope because the end customer removes it immediately, or inside scope because it is plastic. HMRC also publishes exemptions and exclusions for defined situations, including certain transport packaging used to import multiple goods and items designed for long-term storage or reusable presentation. The importer should record why any exception applies and retain the facts that support it.
Distinguish product protection from import transport packaging
HMRC describes an exemption for transport packaging used to import multiple goods safely into the UK. That does not automatically cover every plastic item used during an import. Pallet wrap or a large load-stabilising cover may have a different function from a sleeve around each retail frame, protective film on each glazing panel or an individual ecommerce mailer.
Map packaging levels: unit, retail, grouped, shipping and pallet. Note who applies each layer, what it contains, where it is removed and whether it is present on import. Ask the tax owner to assess each line against the current rule. A supplier should never relabel unit packaging as “transport only” to reduce apparent liability. The product and logistics evidence must support the description.
Measure weights in a repeatable way
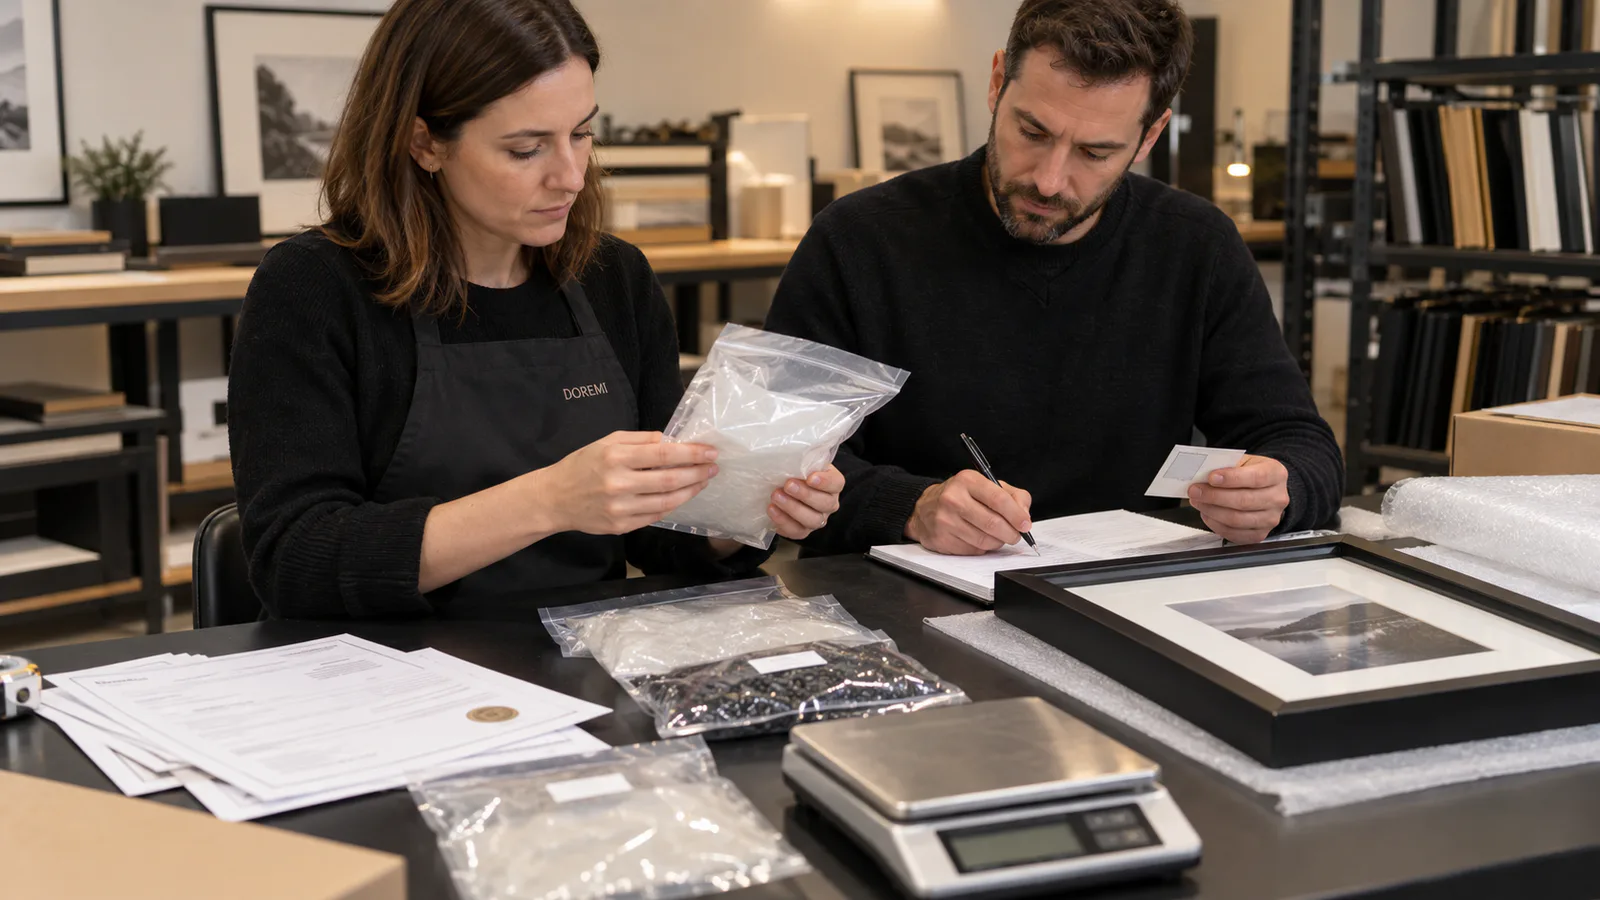
HMRC instructs businesses to work out the weight of each component and excludes the contents of imported filled packaging from the packaging weight. Set a factory method: calibrated scale, tare procedure, number of samples, conditioning state, units, rounding and treatment of labels or adhesive. Weigh a production-equivalent component, not a supplier's theoretical resin usage.
For light films and bags, one item may be below the useful resolution of a bench scale. Weigh a counted batch, subtract tare and divide, while retaining the batch count and raw reading. For multi-material components, record total weight and composition. The responsible tax owner decides which weight the rules require. Keep photos of the setup and a signed record tied to component and revision.
Track both registration tests
HMRC says a business must register if it expects to import or manufacture 10 tonnes or more of finished plastic packaging components in the next 30 days, or has done so in the previous 12 months. The 10 tonnes can combine manufacture and imports. Registration is not assessed only at a calendar year-end, so a rapidly growing frame programme needs a rolling control.
Forecast by component and SKU, then compare actual imports monthly. Include in-scope components whether or not tax will ultimately be payable because they meet the recycled-content threshold; ask the adviser which exempt items still count toward registration. Do not wait until a container is customs-cleared to discover that the threshold was crossed. The importer should own the calculation across all product categories, not only frames.
Apply the 30% test at component level
Plastic packaging components containing 30% or more recycled plastic are not chargeable, but the registration and record position still requires review. HMRC guidance explains that recycled content is worked out for the plastic used in the component and provides rules for multi-material components. A supplier's general statement that its factory “uses recycled plastic” does not establish the percentage in the buyer's exact film, bag or foam part.
Request formulation or production evidence that identifies the component, resin stream, recycled input, calculation period, manufacturing site and traceability method. If a certificate covers a product family, show why the imported component belongs to that family. The importer should verify that the evidence is credible and compatible with HMRC rules, including changes that take effect for pre-consumer plastic from 1 April 2027.
Do not rely on an unsupported recycled-content certificate
HMRC's record guidance says evidence can include manufacturer information or a robust supply-chain audit. Production specifications, contracts and certificates may support the file, but due diligence is still expected. Check the legal supplier, site, component code, validity period, test or calculation basis and whether the claimed input can be traced to actual production purchases.
Look for contradictions. A purchase record for recycled resin does not prove it entered every component. A mass-balance document must match the approach allowed by current rules and the relevant period. A certificate for a 60-micron bag does not automatically cover a 90-micron sleeve from another plant. Record questions and corrections. The aim is not to collect more PDFs; it is to link a defensible conclusion to the imported component.
Control the 2026 rate without hard-coding it into product cost forever
HMRC's 2026 guidance states a rate of £228.82 per tonne from 1 April 2026 for chargeable finished plastic packaging components. Use the rate applicable to the accounting period and confirm updates before quoting landed cost. Store the rate as a dated finance input rather than printing it permanently in the packaging specification.
For sourcing comparison, calculate a scenario by chargeable component and forecast tonnes, then keep tax separate from supplier unit price. This helps the buyer compare material redesign, verified recycled content and component elimination without claiming that any option is automatically compliant. Tax cost is only one decision factor; damage rate, contamination, machinability, appearance and recyclability also matter.
Design changes need evidence, not green adjectives
Replacing virgin plastic with recycled content can change clarity, colour, odour, puncture resistance, sealing and surface cleanliness. Removing plastic can shift damage risk to glazing, corners or finished surfaces. Define performance requirements before development: scratch protection, drop and vibration route, moisture exposure, opening sequence and allowable visual variation.
Run production-equivalent packing and shipping validation. Record material code, thickness, supplier and test observations. Do not advertise a pack as “tax free,” “sustainable” or “100% recyclable” based on a development sample. The tax owner must decide treatment, and environmental claims need their own substantiation. A successful redesign is one that protects the frame and produces traceable data at scale.
Manage filled imports and supplier invoices
For frames imported already packed, the UK importer needs data from the overseas producer before the goods arrive. Add component-level weights and recycled-content evidence to the purchase-order deliverables. State the currency and commercial price separately; PPT is not solved by a line on the factory invoice saying “packaging included.”
Create a shipment schedule that links SKU quantities to packaging revision and component weights. If the same frame is packed differently for retail and ecommerce, use separate configurations. Reconcile the commercial invoice, packing list, incoming inspection and BOM. The importer can then aggregate actual finished components instead of estimating from carton count after the reporting deadline.
Set due-diligence checks by risk
HMRC says businesses that manufacture, import or buy plastic packaging should conduct appropriate due diligence and keep details of the checks. Create a risk-based review rather than a one-time questionnaire. Higher-risk situations include a new supplier, unusually high recycled-content claim, inconsistent documents, rapid material substitution, missing site identity or pricing that appears incompatible with the claimed resin.
Checks can include company verification, specification review, sample comparison, purchase and production records, independent audit or targeted testing where appropriate. No single check suits every component. Record the reviewer, date, evidence, questions, resolution and next review. If a supplier cannot support a claim, the importer should obtain professional guidance rather than instruct the factory to issue a stronger letter.
Keep change control connected to the tax file
Packaging teams often approve a substitute to protect delivery timing. That substitute can change plastic type, finished weight or recycled content. Require written notice before changes to films, bags, foams, tapes, labels, coatings or suppliers. Assign a new revision and decide whether fresh evidence, sample review and tax treatment are required.
Inspect the first production lot against the approved component set. Save sample photographs and scale readings. For reorders, ask the factory to declare “no packaging change” or list changes explicitly. A visually identical transparent bag is not proof of identical formulation. Procurement, quality and finance should receive the same revision notice so that a physical substitution does not remain hidden from reporting.
Build the audit trail around returns and exports
HMRC publishes relief rules for exported or converted components and requires supporting records. A frame programme may import into a UK hub and later export part of the stock. Do not remove those units from calculations casually. Track the original import, component quantities, destination, timing and evidence required for any relief or credit.
Returns also need a documented policy. A customer return does not necessarily reverse the original tax event, and a replacement may introduce another pack. The finance owner should apply current guidance. The supplier can help identify the packaging used for replacements, but should not decide the importer's tax adjustment. Keep commercial and tax records linked without treating logistics estimates as proof.
Importer evidence checklist
- PPT and packaging EPR maintained as separate workstreams
- Each finished plastic packaging component assigned a stable code
- Packaging function and any exemption rationale documented
- Unit, retail, grouped, shipping and pallet layers mapped
- Weights measured with a repeatable method and adequate resolution
- Forward 30-day and rolling 12-month registration tests monitored
- Recycled content supported for the exact component and period
- Supplier certificates checked through risk-based due diligence
- Applicable tax rate confirmed for each accounting period
- Shipment quantities linked to packaging revisions
- Substitutions trigger renewed evidence and tax review
- Export, return and credit evidence handled by the responsible tax owner
Experience scope and project limits
Editorial review: Jessica, Founder & Project Advisor at DOREMI Display. Updated 22 September 2026. Jessica's practical scope covers display-frame specifications, packaging component BOMs, supplier evidence requests, sampling, production communication, quality records and buyer handover. She is not presented as a UK tax adviser, HMRC officer, accountant, polymer chemist, accredited auditor or laboratory.
This article is educational procurement guidance, not tax advice or a conclusion that a component is in scope, exempt, chargeable, sufficiently evidenced or correctly reported. The UK importer and its qualified advisers must confirm registration, classification, recycled-content treatment, weights, rates, returns, due diligence and relief using the rules that apply to the actual transactions and accounting period.
Public sources used for this guide
- Google Search Central: AI features and your website
- HMRC: Plastic Packaging Tax guidance collection
- HMRC: Plastic Packaging Tax steps to take
- HMRC: packaging subject to Plastic Packaging Tax
- HMRC: finished components and substantial modifications
- HMRC: working out packaging weight
- HMRC: records and accounts
- HMRC: due-diligence checks